
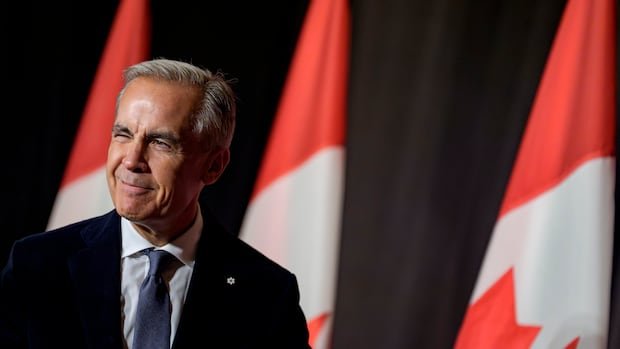

The recent tax reform unveiled by the government during the Canada Investment Summit is set to revolutionize business investments. This new productivity mega-deduction will enable companies to immediately expense the full cost of various investments, spanning sectors such as machinery, equipment, clean energy, and zero-emission vehicles.
Prime Minister Mark Carney expressed the government’s objective to position Canada as the most appealing investment destination among the G7 nations. This initiative builds upon the productivity super-deduction introduced in the previous year’s budget, which initially covered a limited range of investments like equipment, machinery, and technology. However, the expansion now extends eligibility to two-thirds of assets, a significant increase from the initial 15 percent coverage.
During a media briefing, Prime Minister Carney emphasized that the broadened scope of sectors under this deduction would empower business leaders to invest strategically for enhanced productivity, addressing a longstanding issue in the country. This tax reform is designed to incentivize rapid and substantial investments, setting Canada apart as a highly competitive tax environment globally.
Economists, including Randall Bartlett, Deputy Chief Economist at Desjardins, highlighted that this reform could boost Canada’s tax competitiveness, lowering the marginal effective tax rate from 13 percent to 6.4 percent, the lowest among G7 nations. The move is seen as a strategic response to economic uncertainties, potentially encouraging companies to retain operations in Canada and stimulate investments that were previously delayed.
Although the initiative is estimated to cost $36 billion over five years, experts like Jim Stanford, Director at the Centre for Future Work, view it as a progressive step forward. Stanford noted that unlike a generic corporate tax cut, this program necessitates reinvestment in Canadian capital to benefit from the deductions, ensuring a more direct and impactful approach towards economic growth.
In summary, the tax reform aims to propel Canada’s economic landscape by incentivizing investments, enhancing productivity, and reinforcing the country’s position as an attractive investment hub within the global market.